Why emerging telecoms giants need to build an inclusive future and resist bullying
By Industry Contributor 7 October 2026 | Categories: feature articles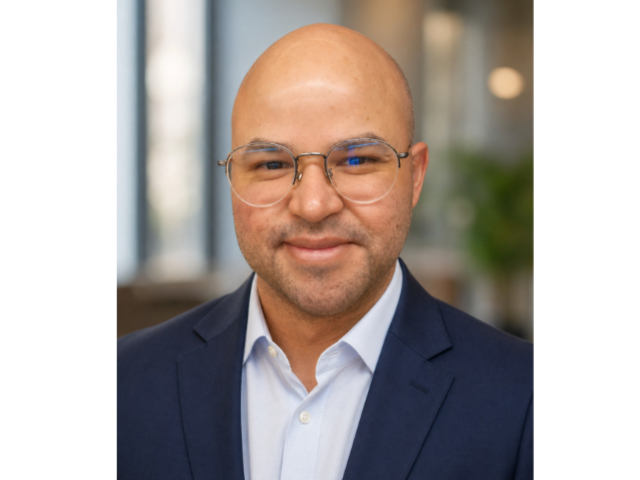
Related Articles
 Veeam Interview - Nine Seconds to Disaster: Explor...

 Trust is the infrastructure South Africa’s AI ec...
 Connectivity providers need greater understanding ...
Jevon King, Chief Commercial Officer at Backspace
A few months ago, ICASA gazetted the National Radio Frequency Plan 2026 and IMT Roadmap 2026, which identify more mid-band spectrum for mobile networks. Separate regulations have been gazetted to open lower bands as shared innovation spectrum. The Electronic Communications Amendment Bill before Parliament would, if passed, let ICASA apply “use it or share it” to unused post-2021 assignments.
This is significant movement on the regulatory front, and anyone in the telecommunications sector will celebrate expanding fibre networks and spectrum access. On the surface, and certainly at a macro level, it is proof of progress. However, in South Africa, running a new, or smaller business presents a different challenge not captured in the bigger picture.
On the ground, the truth is that nominal access to infrastructure does not necessarily mean smaller internet service providers (ISPs) are actually equipped to compete. The picture is far more complicated. South Africa’s telecommunications market does not necessarily suffer from a lack of theoretical network coverage, it suffers from commercial structures that keep smaller providers from being able to compete effectively.
The real barriers are commercial, not technical
An emerging ISP faces a number of challenges when trying to enter or scale in the local market. The most formidable of these is the punitive commercial friction imposed on them by dominant network operators and wholesale providers.
What do these typical commercial barriers look like? First, smaller operators face exorbitant onboarding and implementation fees. This is before they even trade. This pressure is compounded as soon as they start trading in the form of aggressive minimum spend commitments. These are fixed minimum monthly expenditure targets with steep ramp-up periods. The truth is that these were designed for mature businesses with established subscriber bases, certainly not emerging challengers.
This matters because cash flow is the lifeblood of a startup or smaller but growing SME. They need liquidity to manage payroll, billing software and the marketing required to acquire customers. Understanding this, it is clear that forcing smaller players into massive fixed charges before they start generating steady and predictable revenue effectively channels scarce capital away from the fundamentals of running a business and towards a pay-to-play model that adds zero value to the end user. We’ve seen it – failing to meet a minimum spend commitment can shut down a young business almost overnight.
Contract opacity and unilateral risk
Let’s assume a smaller ISP manages to get through the starting blocks. Once they are operating, they find themselves in an environment fraught with contractual risk. Backspace has been in the industry long enough to know just how vulnerable small providers are to wholesale shifts. It is critical that ISPs understand every line, clause and exception in the contracts they sign and shed their reluctance to negotiate aggressively.
We’ve seen a wholesale network provider issue a 30-day notice on a fundamental commercial change. When it was implemented entire product lines became uncompetitive virtually overnight. Businesses that sign up to these standard terms will have very little room to maneuver in situations such as these. Products are discontinued, operational losses have to be absorbed and customers need to undergo painful migrations. Not many businesses have the financial resilience to cushion a blow like this. Small businesses can be wiped out in a flash but this is the reality of the contractual environment they must navigate.
Enablement as another route
Modern businesses, across sectors, are evolving to a model where they rely on flexible, asset-light models rather than heavy capital ownership. This is out of necessity because it makes them more competitive. Similarly, the telecommunications ecosystem is evolving through aggregation to create an environment of enablement for newer entities. Small or new ISPs don’t need to take on direct wholesale risk to deliver exceptional service.
By partnering with enablement partners, ISPs can bypass direct onboarding fees and minimum-spend traps altogether. This is because the aggregators absorb the heavy commercial commitments. This, in turn, allows them to enable smaller operators to compete by giving them immediate access to a basket of services such as fibre, APNs, SIMs and LTE, with flexible terms.
The capital unlocked when smaller or newer ISPs do not have to navigate onboarding fees and minimum spend obstacles enables them to focus entirely on what they do best: Providing differentiated customer service and driving sales.
Regulatory reform
To complement industry-led aggregation, regulatory policy should also evolve. ICASA’s recent field trials exploring dynamic spectrum access demonstrate to the industry that regulator-led reform is possible. However, deploying localised networks remains economically prohibitive under traditional spectrum fee structures.
The Amendment Bill already proposes a 12-month spectrum-fee holiday for secondary users of unused assignments, with preference for community networks and SMMEs. That should be implemented, and paired with flexible local licensing, so smaller operators can actually use shared spectrum without the fee structures designed for national incumbents.
There needs to be more innovation to catalyse widespread connectivity in the country. Regulators would do well to mandate pricing transparency and to enforce reasonable change-control safeguard periods on wholesale contracts. Critically, the regulators should expand low-cost spectrum for community-level deployments.
The buck doesn’t end with the policymakers. Established players and aggregators must continue standardising wholesale service level agreements to protect smaller partners from forced migrations.
Growing into fair giants
Reforming South Africa’s telecommunications market is not about vilifying or punishing the massive incumbents. It is about preventing commercial bullying, so that there can be a fair, competitive environment where ambitious challengers can scale.
Every telecommunications business aspires to grow and become a market leader, but as we build the next generation of large companies in the sector, our shared commitment must be to become “fair giants”. In our view, a fair giant is an operator that enables economic inclusion, fosters innovation and keeps the playing field open for those with growth aspirations of their own.
Most Read Articles
 New Steve Jobs trailer shows a man with a lot on his plate
 AI data environments have different storage requirements
 Chery unveils AiMOGA: Revolutionising the car-buying experience through intellig...
 Lenovo Unveils New Data Storage Solutions to Accelerate IT Modernisation for the...
 Logitech Pebble 2 Combo
 Samsung Galaxy S4 Zoom - white
 New Canva partnership brings local implementation and training to Africa Inbox
 Trust is the infrastructure South Africa’s AI economy will run on

Have Your Say
What new tech or developments are you most anticipating this year?